
Last updated: 13 October 2026. This guide is general information, not personal financial advice. Rates and rules change, so check current details with regulated providers.
Six money mistakes at a glance
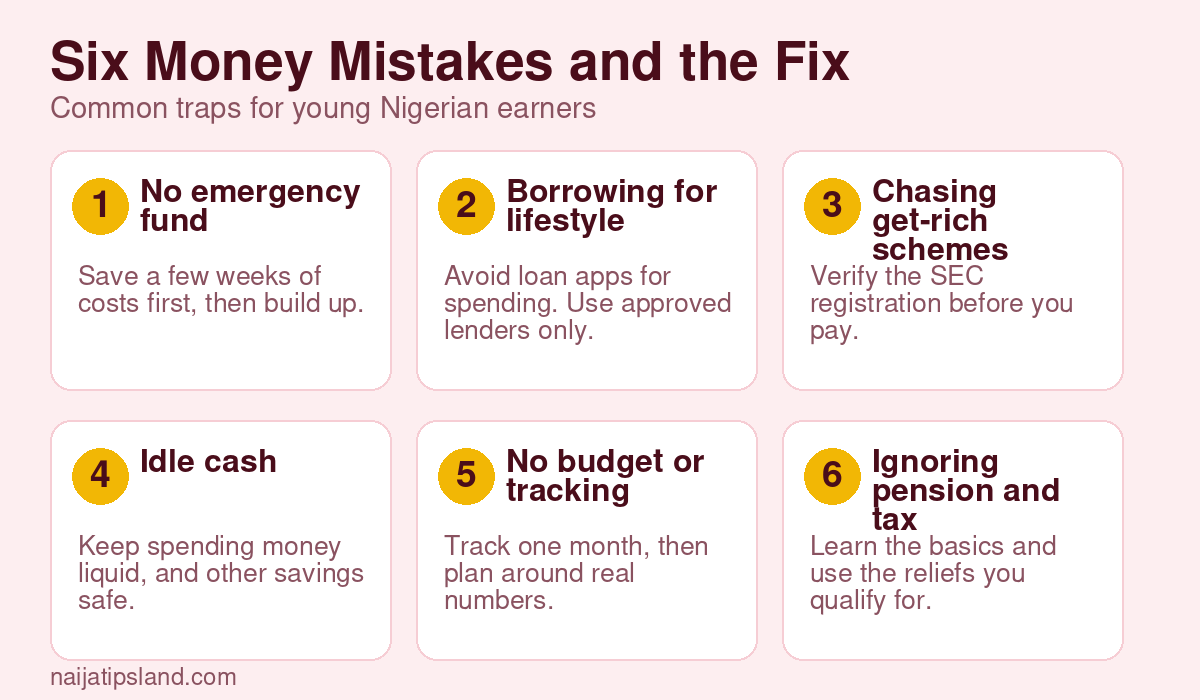
- 1. No emergency fund, so every surprise becomes a crisis or a loan.
- 2. Borrowing for lifestyle, especially through loan apps.
- 3. Chasing get-rich schemes that are not registered with the SEC.
- 4. Letting money sit idle in the wrong place while prices rise.
- 5. Having no budget and no idea where money goes.
- 6. Ignoring pension, insurance and tax basics until they become problems.
Almost everyone makes money mistakes, and in Nigeria’s high-inflation economy they can be costly. This guide covers six of the most common ones among young earners, explains why they happen and shows how to fix them using rules and rates that apply in October 2026. An earlier version of this article carried claims that we could not verify, so we have replaced them with current, sourced information.
Mistake 1: No Emergency Fund
Why it happens: money is tight, so saving feels impossible, and many people assume emergencies will not happen to them.
What goes wrong: a hospital bill, a lost job or a broken phone forces you to borrow, sell assets or skip other bills.
The fix: start small. Set aside one week of basic costs, then build towards one month and, over time, three to six months. Keep it in an account you can reach quickly, such as a bank savings account, which is protected by the NDIC up to ₦5 million per depositor at commercial banks. Automate a fixed amount on payday so you do not rely on willpower. Our full guide on how to save money in Nigeria explains where to keep it.
Mistake 2: Borrowing for Lifestyle, Especially Through Loan Apps
Why it happens: loans are a few taps away, approvals are fast and repayment feels far off.
What goes wrong: short loans can carry high costs, and missing a repayment can lead to penalties and, historically, harassment. Borrowing to fund spending rather than something that pays you back creates a cycle that is hard to leave.
The fix:
- Borrow only for genuine needs, and only what you can repay on time.
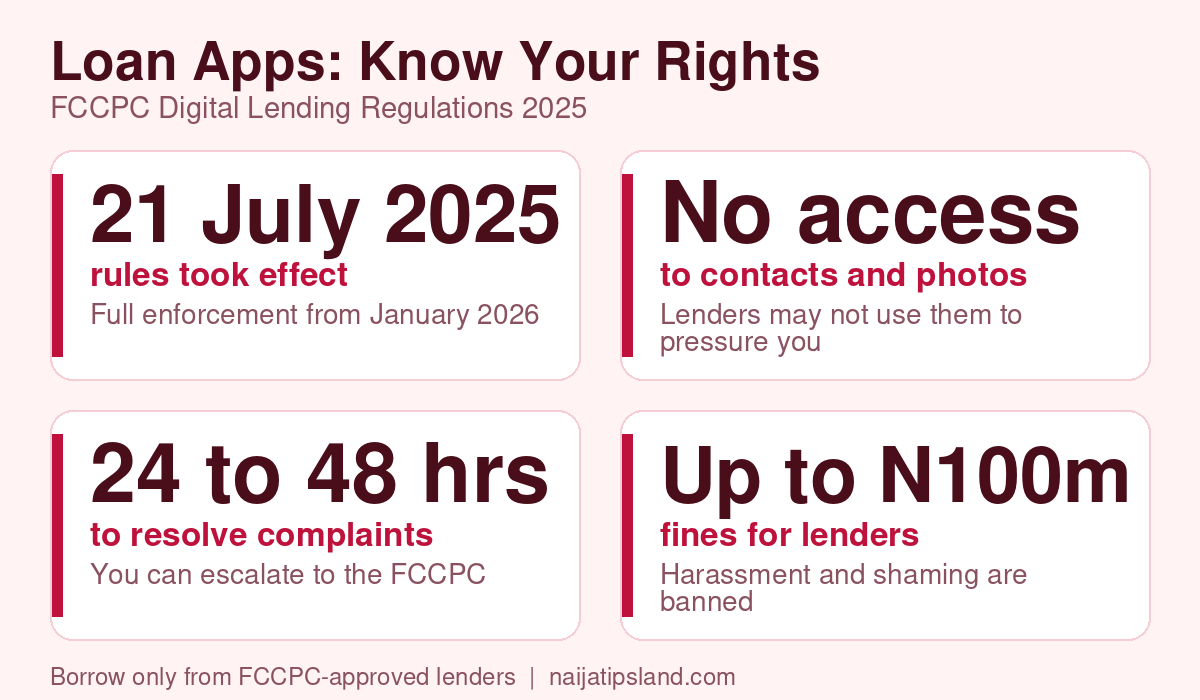
- Use lenders approved by the Federal Competition and Consumer Protection Commission (FCCPC). Under its 2025 digital lending regulations, which took effect on 21 July 2025 with full enforcement from January 2026, lenders must disclose the full cost of a loan before you accept it.
- Know your rights. Lenders may not access your contact list, call logs or photos, and harassment and shaming are banned. Complaints must be handled within 24 to 48 hours, you can escalate to the FCCPC, and lenders can face fines of up to ₦100 million.
- Pay off the most expensive debt first, and do not borrow from one lender to repay another.
Mistake 3: Chasing Get-Rich Schemes
Why it happens: when salaries do not stretch, offers of fast returns are tempting, and friends or influencers seem to be winning.
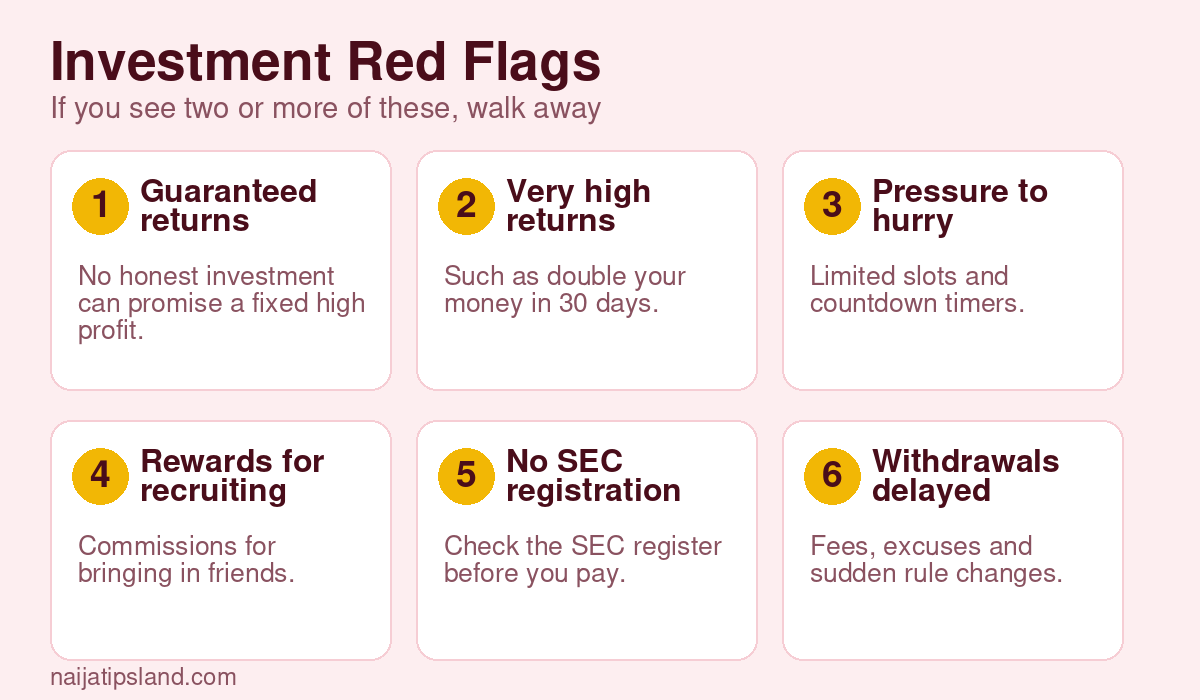
What goes wrong: unregistered schemes collapse and investors lose their money. CBEX, which promised a 100% return in 30 days and was not registered with the SEC, collapsed in April 2025, and reported losses ran into the hundreds of billions of naira or more. In May 2026 the SEC again warned about schemes promoted on WhatsApp, Instagram, Telegram, Facebook and TikTok.
The fix: the Investments and Securities Act 2025 says only entities registered with the SEC may offer investment services or solicit funds. Verify the company and its promoters on the SEC’s register before you invest, and treat guaranteed or very high returns as a warning. Promoting an unregistered scheme can attract a fine of at least ₦20 million, up to 10 years in prison, or both, so ask yourself why a promoter is willing to risk that.
Read our guides on avoiding internet scams and WhatsApp scams.
Mistake 4: Letting Money Sit in the Wrong Place
Why it happens: keeping cash feels safe, and investing feels complicated.
What goes wrong: with inflation at 15.39% in August 2026, money that earns little loses buying power. At the other extreme, putting emergency money into something you cannot reach, or something risky, can leave you stuck.
The fix: match the place to the purpose. Keep emergency money in an accessible, insured account. For money you will not need for two or three years, options such as FGN Savings Bonds can pay a fixed rate from ₦5,000. The October 2026 offer paid 13.071% for two years and 14.071% for three years, which is close to, but a little below, the inflation rate, so do not expect to get rich. Keep your expectations realistic.
Mistake 5: No Budget and No Tracking
Why it happens: budgeting seems tedious, and many people assume they know where the money goes.
What goes wrong: small daily spending on data, transport, food and subscriptions adds up, and raises in income vanish into higher lifestyle costs.
The fix: track every expense for one month using a notebook, spreadsheet or app. Group it into essentials, savings and debt repayment, and personal spending. Then set limits for the coming month. Revisit it whenever your income, rent or prices change. Our guide to Nigeria’s cost of living can help you set realistic categories.
Mistake 6: Ignoring Pension, Insurance and Tax Basics
Why it happens: retirement feels distant and tax seems to be someone else’s business.
What goes wrong: without a pension, no income stream arrives at retirement. Without insurance, one accident can wipe out savings. Without understanding tax, you can overpay or miss reliefs.
The fix:
- Pension: employees contribute through a Pension Fund Administrator. Self-employed and informal workers can use the Personal Pension Plan, the successor to the micro pension plan under the Pension Commission’s September 2025 guidelines.
- Tax: under the Nigeria Tax Act 2025, effective 1 January 2026, the first ₦800,000 of annual taxable income is taxed at 0%, tenants can claim rent relief of 20% of annual rent up to ₦500,000, and approved pension contributions are generally deductible. Keep records, and get advice if your situation is complex.
- Insurance: look into health cover and, where relevant, life or property cover from licensed insurers.
A Simple Reset You Can Do This Week
- List what you earn and what you owe.
- Cancel one subscription or cost you do not need.
- Set up an automatic transfer, even a small one, on payday.
- Check that every lender and investment you use is registered.
- Write down one financial goal and a date.
Three Short Examples (Hypothetical)
- The surprise bill: Ada earns ₦180,000 a month and has no savings. A ₦120,000 medical bill arrives, so she takes a loan app advance with fees, and spends the next three months repaying it instead of saving. If she had saved ₦10,000 a month for a year, she could have covered most of the bill herself.
- The too-good offer: Emeka puts ₦200,000 into a platform that promises to double it in a month, because a friend showed screenshots. The platform is not registered with the SEC and stops paying out. He later learns that the screenshots were easy to fake.
- The idle cash: Bisi keeps ₦500,000 in a current account that pays almost nothing. Over a year, prices rise by roughly 15%, so the same money buys noticeably less. Moving the money she would not need for two years into a regulated, fixed-rate product would not make her rich, but it would limit the damage.
A Checklist Before You Borrow
- Do I need this, or do I merely want it now?
- What is the total I will repay, including fees and interest?
- Can I repay on time from income I already have?
- Is the lender approved by the FCCPC?
- Have I read the terms, and do I have a copy?
- What is my plan if my income falls for a month?
The Mindset Behind Money Mistakes
Many mistakes come from social pressure rather than ignorance. People spend to keep up, lend money they cannot afford to lose or join schemes because everyone else seems to be winning. It helps to decide your priorities in advance, to talk to one trusted person about your goals and to remember that other people’s highlights are not their full financial picture.
Frequently Asked Questions
What is the most common money mistake?
Not having an emergency fund is among the most common, because it pushes people into debt when something goes wrong.
Are loan apps illegal in Nigeria?
No, but digital lenders must register with the FCCPC and follow rules on disclosure, privacy and fair collection. Harassment and accessing your contacts and photos are prohibited.
How do I know if an investment is legitimate?
Check that the company and promoter are registered with the SEC, be suspicious of guaranteed returns and never invest money you cannot afford to lose.
Is it too late to start saving or investing?
No. Starting small today is better than waiting for a perfect moment.
Should I pay debt or save first?
Build a small emergency fund, then pay off the most expensive debt aggressively, and continue saving in parallel at a modest level.
Related Guides
- How to save money in Nigeria in 2026
- Financial literacy checklist for young Nigerian adults
- How to avoid internet scams
- How to avoid POS agent fraud in Nigeria
Sources
- Nairametrics: The CBN’s rate reset, easing with discipline
- Nairametrics: NDIC warns Nigerians against unregulated investments
- Nairametrics: FGN Savings Bond rates fall to 13.07% and 14.07%
- Credence Law: FCCPC consumer lending regulations 2025
- Legit.ng: FCCPC cracks down on loan apps, 7 key rules
- The Sun: SEC urges Nigerians to report illegal investment schemes
- Legit.ng: SEC warns Nigerians as investment schemes flood social media
- NairaCompare: The complete guide to personal pensions in Nigeria
- Safeguard Global: Nigeria Tax Act 2025 goes into effect on 1 January 2026
Join the discussion
Have you tried this, or do you have a question we did not answer? Be the first to share your experience. Leave a comment below. Every comment is read by the editor before it appears.