

Last updated: 13 October 2026. This guide is general information, not financial or tax advice. Returns are never guaranteed, and rates change with every offer. Verify any provider with the SEC, CBN or other regulator before you commit money.
Passive income in Nigeria at a glance
- The truth: almost no income is completely passive. Most sources need money, time, skill or all three at the start, and some upkeep afterwards.
- The low-effort options: interest on bonds and deposits, and dividends from regulated investments. The October 2026 FGN Savings Bond paid 13.071% for two years and 14.071% for three years, from ₦5,000.
- The reality check: inflation was 15.39% in August 2026, so many safe returns barely keep up with prices.
- The big risk: scams that promise “earn while you sleep” returns. Only SEC-registered operators may offer investment services.
“Passive income” is one of the most abused phrases online. It describes money that arrives with little ongoing effort, such as interest, dividends or rent, but it almost always requires an upfront investment of capital, time or skill, and it always carries risk. An earlier version of this guide gave examples without enough warnings or sourced figures, so we have rewritten it around what is realistic in Nigeria today, the rules that apply and the scams to avoid.
How Passive Is It? Compare the Options

1. Interest From Bonds and Deposits
The most straightforward form of regular income is interest on money you lend to a bank or the government.
- FGN Savings Bonds: issued by the Debt Management Office, backed by the full faith and credit of the Federal Government and listed on the Nigerian Exchange. You can start from ₦5,000, units cost ₦1,000, and the maximum is ₦50 million. Interest is paid quarterly and the principal returns at maturity. The rate is fixed on the day you buy, and the October 2026 offer paid 13.071% on the two-year bond and 14.071% on the three-year bond, down from 14.12% and 15.12% in September.
- Fixed deposits: banks pay a negotiated rate if you lock money for a period. Deposits are insured by the NDIC up to ₦5 million per depositor in commercial banks and up to ₦2 million in microfinance and certain other banks.
- Treasury bills and money market funds: short-term instruments accessed through banks, stockbrokers and fund managers. Check who is handling your money, and use only SEC-registered fund managers.

Limits: interest income can be below inflation, so your money may not grow in real terms, and your funds are locked until maturity or restricted by penalties. Tax treatment varies by product, so check it before you invest.
2. Dividends From Shares and Funds
Some listed companies pay part of their profits to shareholders, and some funds pass on income. Dividends are not guaranteed, share prices can fall and you need a licensed stockbroker. Read company reports, diversify and never invest money you may need soon. The effort is front-loaded: you must research before you buy and review regularly afterwards.
3. Rental Income
Renting out property can generate regular income, but it needs significant capital, and it is not hands-off. You face vacancies, repairs, tenant disputes, agent fees and legal requirements. Read our guide on the mistakes first-time landlords make before you buy. Note that under the Nigeria Tax Act 2025, rental income is part of your taxable income, so keep records.
4. Digital Products and Content
Courses, templates, ebooks, photography, music and videos can be sold repeatedly after you create them, and creators can earn from ads or sponsorships if they build an audience. But this takes a lot of unpaid work first, results vary enormously and many creators earn little. Treat it as a long-term project, test small, and follow advertising rules if you promote products. See our guides on social media growth and side hustles.
5. Affiliate and Referral Income
You can earn commissions by recommending products you use. It works best when you have an audience that trusts you and you disclose the commission clearly. Never recommend something you have not checked, and avoid schemes that pay mainly for recruiting others.
6. Pensions and Annuities (Long-Term)
Retirement savings are the most dependable long-term passive income plan for many people. Employees contribute through a Pension Fund Administrator, and self-employed and informal workers can use the Personal Pension Plan that replaced the micro pension plan under the Pension Commission’s September 2025 guidelines. The income starts at retirement, so it is a slow, steady build.
What About Crypto and “Staking”?
Some platforms advertise daily or monthly returns from digital assets. These products carry high risk, and many collapse. The Investments and Securities Act 2025 brings digital asset platforms under the SEC, which says unregistered platforms are illegal. Read our guide on buying Bitcoin and USDT in Nigeria before you consider anything in this area.
Red Flags: How Passive-Income Scams Work
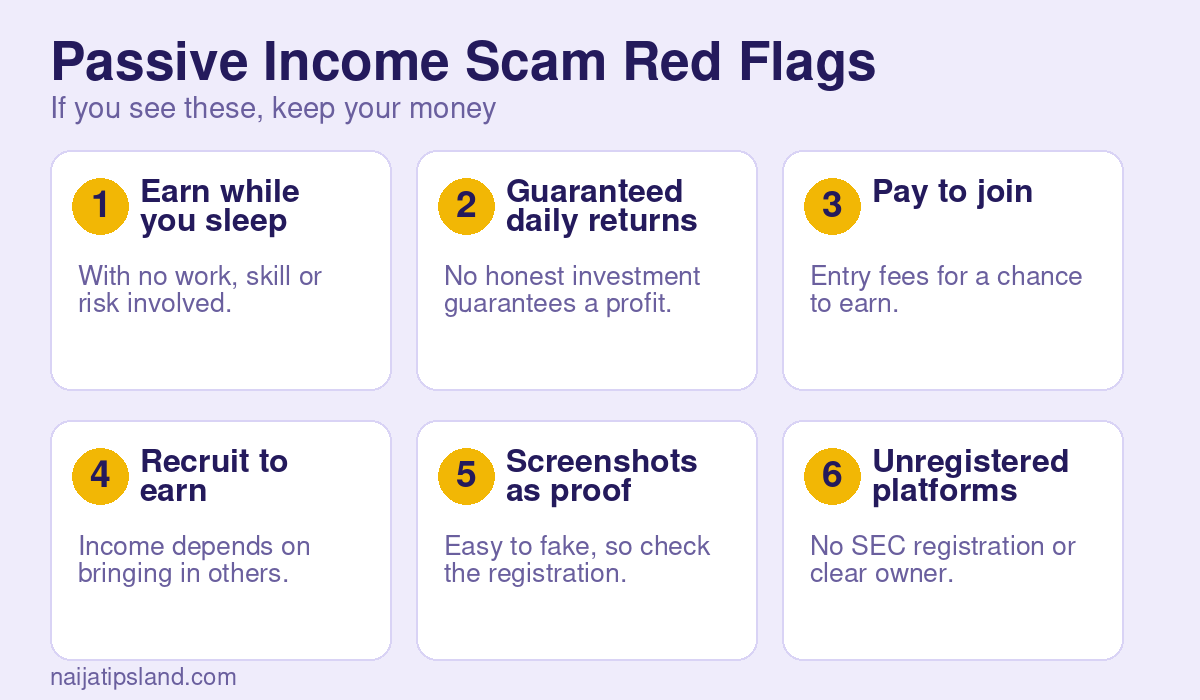
CBEX, which promised a 100% return in 30 days, collapsed in April 2025 with enormous reported losses, and it was not registered with the SEC. In May 2026 the SEC warned again about schemes promoted on WhatsApp, Instagram, Telegram, Facebook and TikTok. Promoting an unregistered scheme can attract a fine of at least ₦20 million, up to 10 years in prison, or both. Before you invest, check that the operator is registered, ask how the returns are earned and walk away if the answer is vague. Our guides on internet scams and common money mistakes show more warning signs.
Tax and Record-Keeping
- Income is generally taxable unless an exemption applies. Under the Nigeria Tax Act 2025, effective 1 January 2026, the first ₦800,000 of annual chargeable income is taxed at 0% and the top rate is 25%.
- Keep records of interest, dividends, rent and expenses.
- If you run a business around your income, see our guide on registering a business name.
- Ask a qualified adviser about your own situation.
A Realistic Way to Start
- Build an emergency fund and clear costly debt first.
- Decide how much you can lock away without hardship.
- Start with the simplest, most regulated option, such as a savings bond or a fixed deposit.
- Add other sources slowly, and only once you understand them.
- Review your income and prices every quarter.
A Worked Example With FGN Savings Bonds (Hypothetical)
Suppose you invest ₦500,000 in the three-year FGN Savings Bond at the October 2026 rate of 14.071% a year. Before any tax, the annual interest would be about ₦70,355, paid in four quarterly instalments of roughly ₦17,589, and you would get your ₦500,000 back at maturity. If prices rise by 15% a year over the same period, the interest roughly keeps pace with inflation but does not beat it, so the real value of your money stays about flat. That is a decent outcome for low-risk money, but it shows why you should not expect to become wealthy from safe, passive sources alone.
Passive Income Myths
- “It takes no work.” Even interest income needs you to research, compare and monitor products. Business-type sources need far more.
- “More risk always means more return.” Higher risk can simply mean a higher chance of losing money. Scams advertise returns that no real business can deliver.
- “Everyone is doing it.” Success stories are visible, but losses are rarely posted.
- “I can start with nothing.” Some options need little money, but most need time, skill or both.
Frequently Asked Questions
Is passive income real?
Some income needs little ongoing effort, such as interest and dividends, but it needs capital and carries risk. Truly effortless, risk-free income does not exist.
What is the safest passive income in Nigeria?
Federal Government securities such as FGN Savings Bonds and insured bank deposits are among the lower-risk options, but returns may be below inflation.
How much money do I need to start?
FGN Savings Bonds start at ₦5,000. Other options, such as property, need far more.
Can I earn passive income online without capital?
You can create digital products or content with little money, but it takes a lot of time and income is uncertain.
How do I check whether an investment platform is legal?
Confirm its registration with the SEC, and avoid any platform that guarantees returns or pays you to recruit.
Related Guides
- How to save money in Nigeria in 2026
- Financial literacy checklist for young Nigerian adults
- Side hustle ideas for young Nigerian adults
- 12 mistakes first-time landlords make in Nigeria
Sources
- Nairametrics: FGN Savings Bond rates fall to 13.07% and 14.07%
- Tribune: FG offers N50m FGN Savings Bonds at up to 14.07 percent
- Blueprint: DMO cuts FGN Savings Bond rates as October subscription opens
- Nairametrics: NDIC warns Nigerians against unregulated investments
- The Sun: SEC urges Nigerians to report illegal investment schemes after CBEX collapse
- Legit.ng: SEC warns Nigerians as investment schemes flood social media
- NairaCompare: The complete guide to personal pensions in Nigeria
- Safeguard Global: Nigeria Tax Act 2025 goes into effect on 1 January 2026
- Nairametrics: The CBN’s rate reset, easing with discipline